Retirement Life
23 September 2026
What's your personal inflation rate?
If you’ve been wondering why your retirement income doesn’t stretch as far as it used to, you’re not imagining things and it’s not because you’re being careless with your budgeting. We often talk about the inflation rate as if we all experience the same price increases. But in reality, everybody’s inflation rate is different – and this is because it’s linked to what you buy. We know people on low incomes have different spending patterns to those on high incomes, and that impacts how inflation affects them.
The cost of living for retirees
The cost of living for retirees is rising faster than other New Zealanders. Most people are familiar with the Consumer Price Index (CPI). However, Stats NZ also calculates a Household Living Costs Price Index (HLPI) for different segments of our population including beneficiaries, Māori, superannuitants, people in different income brackets and people in different spending brackets.
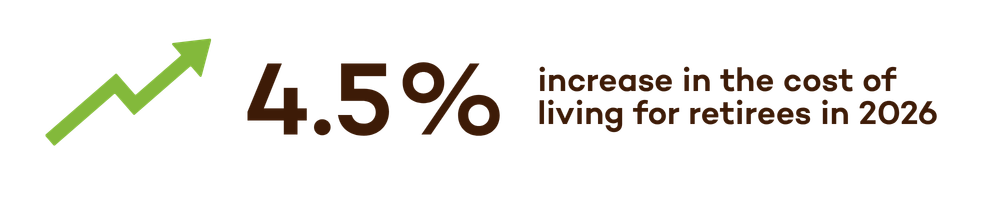
The cost of living for the average New Zealand household, as measured by the HLPI, rose by 3.2% in the year to June 2026. But for those on the pension, costs went up 4.5%. In comparison, people with high levels of spending (and presumably the high incomes to match) saw a cost increase of only 1.9%.
The reason for the differences lies in what these groups spend their money on. Let’s look at some of the differences.
Retirees versus a young family starting out
A young couple with a family and a mortgage spend a large chunk of their income on things like childcare, commuting costs and mortgage interest. Interest rates have fallen in recent times, and so this has had a beneficial effect on their living costs.
Retirees on the other hand spend most of their income on utility costs, such as rates, power and phone, and on essentials such as food, petrol, healthcare and insurance. These expenses are difficult to cut back on as they’re the necessities of life. Electricity prices increased by about 8% in the last year, and that’s on top of an 8% increase the previous year. Petrol prices, meanwhile, have gone up by 15%, the average local authority rates bill is up about 9% and insurance costs have soared. All households spend money on these things, but because retiree incomes are so low, they make up a bigger proportion of total household living costs.
Why you shouldn’t stop going out for dinner though
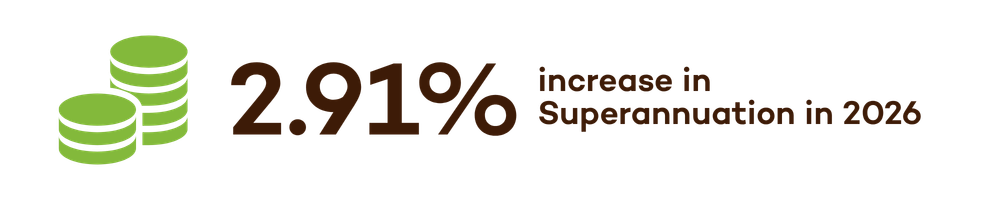
Despite the 4.5% increase in living costs pensioners saw, NZ Super increased by only 2.91% on 1 April 2026. That’s because it’s linked to the increase in net average wages, not living costs. If living costs for retirees were to increase by 2% more than their income for ten years, their pension purchasing power would reduce by nearly 20%. That’s a substantial drop which many retirees would not be able to sustain.
Cutting back on spending is not a practical solution to the inflation problem for retirees. There is usually little room to move in a retirement budget, as most spending is on essentials. Besides which, retirement is supposed to be enjoyed and being overly frugal is counter to that. Inflation doesn’t mean you should stop travelling, going out for dinner or doing all the other things you enjoy.
But knowing what your own inflation rate is can help identify the pressure points on your living costs so you know where to focus your attention. While many costs are out of your control, you can shop around for better deals on some things such as power, internet and phone costs and insurance.
Investing for income: the best defence can be offence
Sometimes people react to higher living costs by becoming more defensive and protective with their retirement savings and invest conservatively as a result. In fact, the best defence against inflation is to have at least some of your investments in growth assets such as shares, as this can provide a higher return to help offset your cost increases.
This is particularly important for people starting out in retirement, as their retirement savings may well have to last thirty years. While it’s always important to have spending money on hand in safe investments, such as bank deposits, it’s also important to think about the long term and the effects of inflation on spending power.
The key message here is that the Consumer Price Index doesn’t measure your personal inflation rate. Understanding where your own costs are increasing, controlling the expenses you can and ensuring some of your investments have the potential to grow in value will make a big difference to how long your money lasts.
Investing for income with Lifetime
Lifetime Retirement Income Fund, uses both growth assets as well as more defensive assets, which are used to provide regular payments for 20 to 30 years.
Learn more about how we invest for income here: Investing for Income
The advice given here is general and does not constitute specific advice to any person.
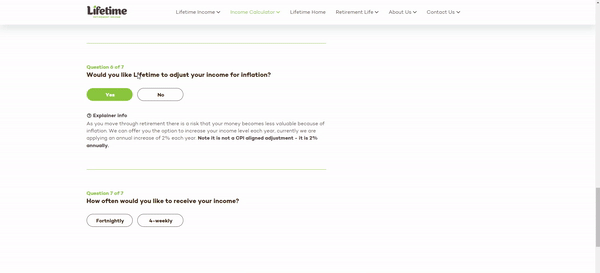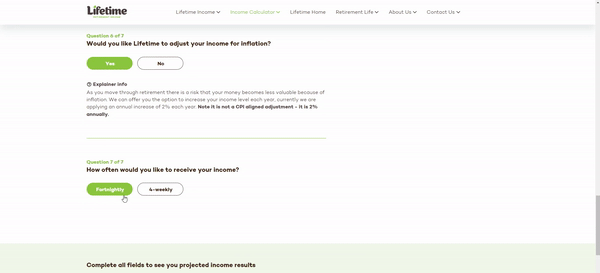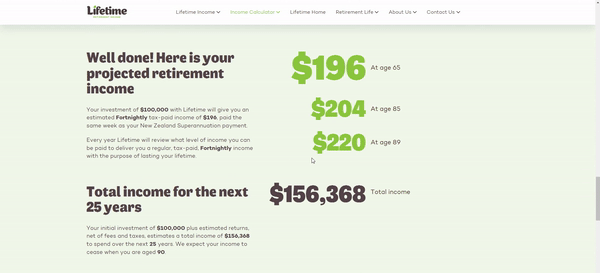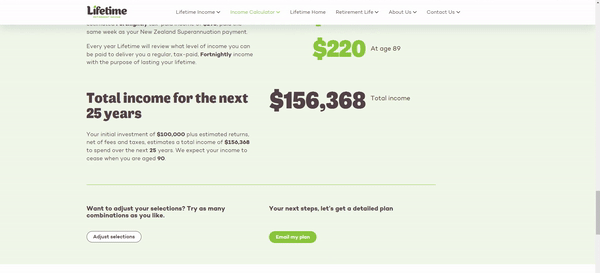
How much could you get per fortnight?
Written by:
Liz Koh
Liz Koh is a money expert who specialises in retirement planning.
Turn your retirement savings into a regular income.